Zero-based budgeting has a reputation problem. Say the phrase and most people picture a color-coded spreadsheet with forty line items and a formula that breaks the moment you touch it. That’s one way to do it. It’s not the only way, and if spreadsheets make your eyes glaze over, there’s a version of this method that works entirely on paper, in your head, or with a five-minute banking app check-in.
What zero-based actually means
The core idea is simple: every dollar of income gets assigned a job before the month starts, so income minus all assigned spending equals zero. That doesn’t mean you spend everything — money assigned to “savings” or “debt payoff” is still a job. It just means nothing is left unaccounted for, floating around waiting to get spent on something random. You can do this with three sticky notes as easily as with software.
The envelope method, modernized
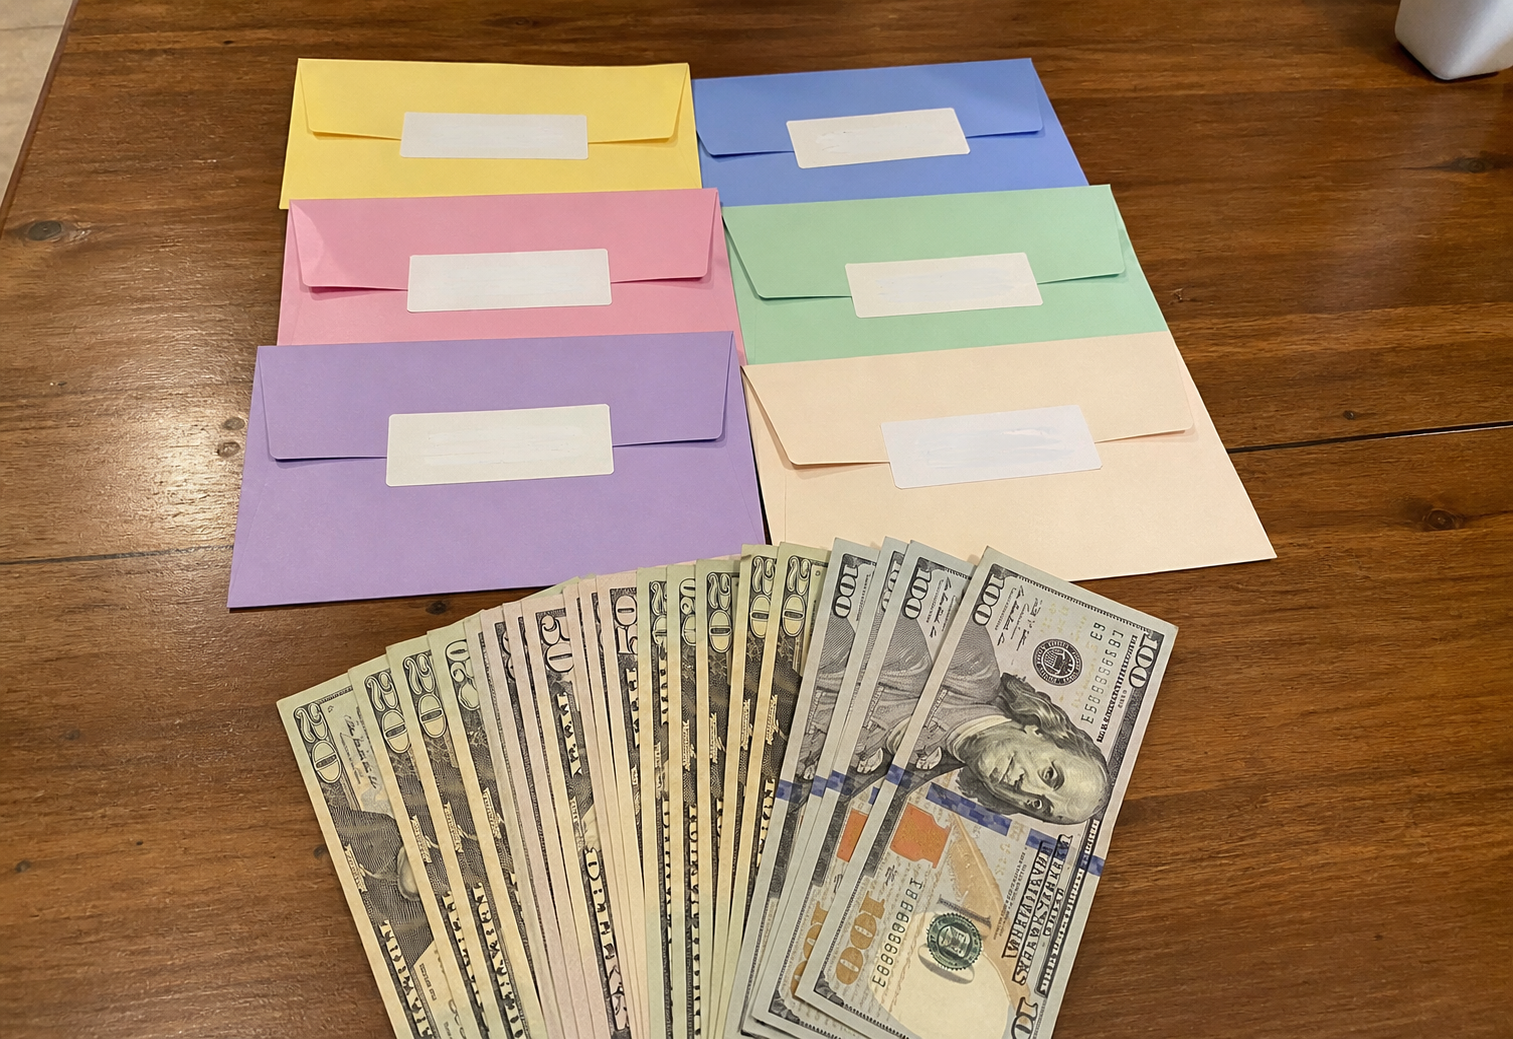
The classic cash-envelope system still works, and you don’t need physical cash to use its logic. Open a free second checking account or use the “savings pockets” or “bill pay” feature most banking apps now offer. Create four or five virtual envelopes: Bills, Groceries, Gas, Fun Money, Savings. The moment you get paid, transfer your planned amount into each one. Then simply spend from your main account as normal, but check your envelope balances before making non-essential purchases. When the Fun Money envelope hits zero, you’re done spending on fun for the month — no math, no spreadsheet, just a number you can see.
The 100-dollar bill method for people who think in round numbers
If percentages and formulas lose you, try thinking in blocks of $100 instead. Say your take-home pay is $3,800. That’s 38 blocks of $100. Assign each block a job out loud or on a sticky note: “12 blocks to rent, 4 to groceries, 2 to gas, 3 to phone and utilities, 5 to debt payoff, 4 to savings, 3 to fun, 5 to the irregular-expenses fund.” Thirty-eight blocks, thirty-eight jobs, zero left over. This works because most people can do rough arithmetic with round hundreds far more easily than with percentages or decimals.
Adjusting the system when your paycheck isn’t the same every time
Zero-based budgeting gets a bad reputation with freelancers, gig workers, and anyone on commission because the method assumes you know your income before the month starts. You can still run it — you just assign jobs to a rolling average instead of a fixed number. Take your last three to six months of income, find the lowest month, and build your zero-based plan around that floor amount only. Anything you earn above the floor in a good month doesn’t get spent immediately; it goes into a dedicated “income smoothing” envelope first. Then, in a lean month, you draw from that envelope to keep every other category funded at its normal level, rather than scrambling to cut groceries or gas mid-month. A rideshare driver averaging $3,200 a month but ranging from $2,400 to $4,100 would build the whole zero-based plan around $2,400, routing the extra $800-1,700 from stronger months straight into the smoothing envelope. Within two or three months, that envelope usually holds enough buffer that even a genuinely bad month doesn’t force a single category to go unfunded.
A five-minute weekly check-in instead of daily tracking
You don’t need to log every purchase to run a zero-based budget. Instead, pick one day a week — Sunday evening works well for most people — and spend five minutes checking each envelope or category balance against what’s left in the month. Ask three questions: Am I on pace? Did anything unexpected happen this week? Does anything need to shift? That’s the entire review. It’s far more sustainable than daily logging, and it catches problems while there’s still time to adjust, rather than after the month is already over.
Handling the “leftover money” problem
One reason people abandon zero-based budgeting is they don’t know what to do when a category has money left at month’s end. The rule that keeps it simple: leftover money in a spending category (groceries, gas, fun) rolls straight into savings or debt payoff — it doesn’t carry forward to next month’s spending. This does two things. It removes the temptation to blow through a surplus just because it’s “extra,” and it means every month genuinely does start at zero, with last month’s discipline compounding instead of resetting.
Why this beats a spreadsheet for most people
Spreadsheets fail for the same reason gym memberships fail: they demand a level of ongoing maintenance that doesn’t match most people’s actual habits. A visual, low-friction system — envelopes you can glance at, round numbers you can do in your head — survives busy weeks, bad months, and general life chaos in a way a formula-heavy sheet rarely does. The goal of zero-based budgeting was never precision to the penny. It’s making sure every dollar has a purpose before it disappears into “I don’t know where it went.” You can hit that goal with sticky notes just as well as with a $19-billed-annually app subscription.